Revolut’s UK Loans Strategy Keeps Balance-Sheet Risk Light
Revolut has launched unsecured personal loans in the UK, extending Europe’s most valuable fintech into a market traditionally led by high street banks.
But the company’s financial model remains deliberately conservative.
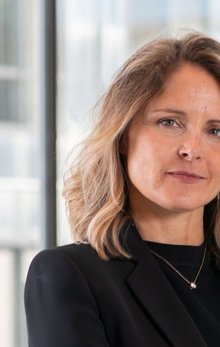
Francesca Carlesi, CEO of Revolut UK, tells Reuters that the bank intends to sell much of its credit exposure through securitisation and maintain a loan-to-deposit ratio of around 6%.
That approach echoes a long-standing position from Co-Founder and CEO Nik Storonsky: Revolut wants to originate credit, not retain it.
Revolut has begun offering unsecured personal loans to UK customers, marking the entry of Europe’s most valuable fintech into a segment traditionally controlled by established high street lenders.

Despite the expansion, the company is taking a deliberately cautious approach to its balance sheet.
Francesca Carlesi, CEO of Revolut UK, tells Reuters that much of the credit exposure will be sold to investors through securitisation, while the business aims to keep its loan-to-deposit ratio at around 6%.
The strategy reflects a position Nik Storonsky, Revolut’s Co-Founder and CEO, has maintained for years: the company wants to create and distribute credit, rather than retain it on its own books.
That model will now face a real-world test in the UK, where Revolut must assess whether it can lend to millions of consumers without absorbing the underlying credit risk, and how resilient that approach would be if investor demand for loan assets declines.
- Unsecured personal loans from £2,000 to £25,000 (US$2,663 to US$33,290)
- Interest rates ranging from 6.9 to 29.3%
- A target loan-to-deposit ratio of about 6%, against roughly 100% at a typical bank
- phased rollout to its 14 million UK customers over the coming months
- A credit card planned for the near future, with mortgages to follow.
The initial release is limited to a selected customer group, with wider availability planned across Revolut’s 14 million UK users in the months ahead.
In a LinkedIn post, Francesca says: “We are committed to deliver responsible borrowing on our customers’ terms, right where they already manage their existing financial lives.
“We’ve made loans available to a limited number of customers as we scale up, with access expanding in the coming weeks and months.
“This is just the first step in building our lending ecosystem as we grow our operations across the UK.”
A Revolut spokesperson confirms that borrowing amounts will run from £2,000 to £25,000 (US$2,663 to US$33,290), with annual interest rates between 6.9% and 29.3%.
We are committed to deliver responsible borrowing on our customers’ terms, right where they already manage their existing financial lives.”
Revolut partners:
Google Cloud: runs Revolut’s core infrastructure. In September 2025, the companies signed a multi-year deal expanding the partnership and bringing Google Gemini models into Revolut fraud detection, supporting its target of more than 100 million customers.
Mastercard: has partnered with Revolut since its 2015 launch. The companies have a global deal under which Mastercard powered Revolut’s first US cards and committed to at least half of its European cards.
Visa: supplies Revolut cards and has issued them in Europe since July 2017. The companies extended the partnership through Visa Direct, letting Revolut Business clients send cross-border payments using only a card number.
Executives
Francesca Carlesi
CEO - Revolut Bank UK
Nik Storonsky
Founder & CEO